Rising US bond yields are bad news for the Indian stock market — it is one of the reasons you will keep hearing on business news whenever Indian stocks have a rough week. Take Monday, 28th September 2026: the Sensex closed down 1,124 points (1.52%) at 72,771.72, and the Nifty 50 closed down about 360 points (1.56%) at 22,780, with rising US bond yields flagged alongside crude oil prices spiking on West Asia tensions. The oil story is easy to picture — costlier crude means a bigger import bill for India. But “rising US bond yields” is the one that leaves most readers scratching their heads. What does a number from an American government bond have to do with a stock in Mumbai? Here’s the plain-language version.
First, what is a “US bond yield”?
When the US government needs to borrow money, it sells bonds. In simple terms, that’s a loan: whoever buys the bond is lending money to the government, which promises to pay it back later with interest. The “yield” is simply that interest rate, expressed as a percentage per year.
The one everyone quotes is the 10-year US Treasury yield — the annual return you’d earn for lending the US government money for ten years. As of late September 2026, that yield was sitting at around 5.1–5.2%, its highest level in nearly two decades.
Why “risk-free” is the key word
Here’s the part that matters. Nobody seriously expects the US government to fail to pay back this kind of debt. So this 5%-plus return isn’t just a good return — it’s considered a virtually risk-free one.
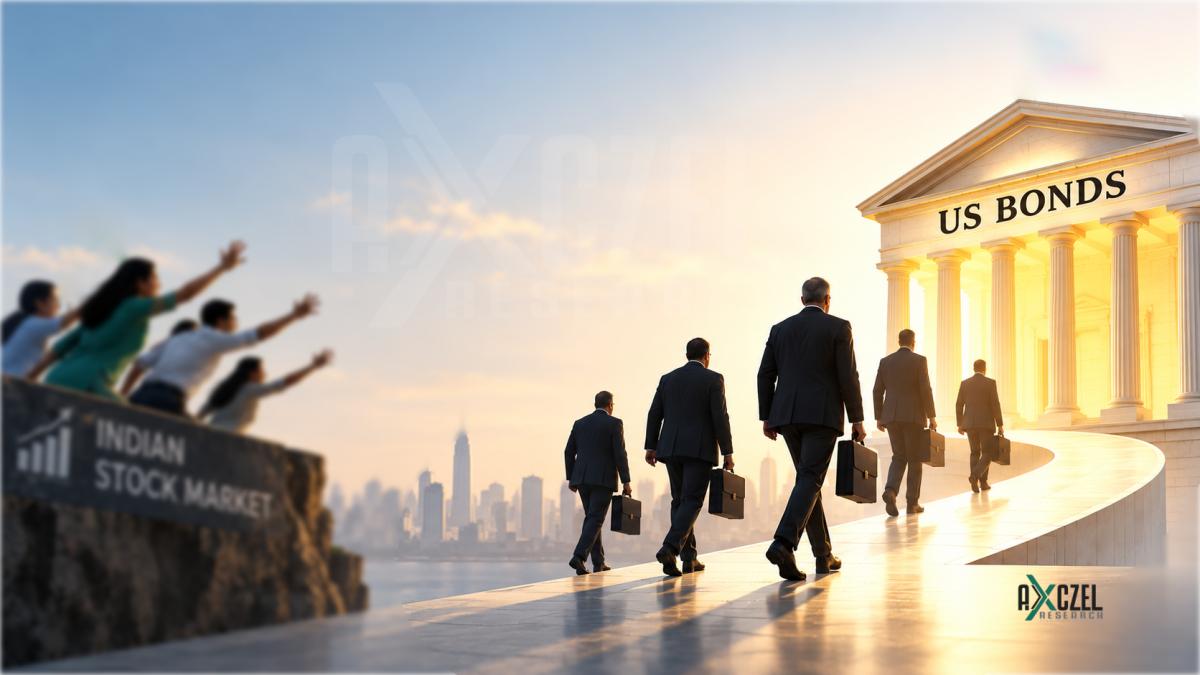
Now put yourself in the shoes of a large global fund manager sitting on billions of dollars, deciding where to place that money. One option: lend it to the US government, sit back, and collect a guaranteed 5%-plus every year. The other option: buy shares in an Indian company, where the return could be higher — or lower, if the company disappoints, the currency moves against you, or the market falls.
When the safe option pays only a couple of percent, taking a risk on Indian stocks for a shot at a much bigger return looks like an easy call. But when the safe option pays over 5% for doing nothing at all, that risky bet suddenly needs to promise a lot more to be worth taking. This is really the whole story: rising US yields quietly raise the bar that Indian stocks — and every other “risky” investment on the planet — has to clear to attract the same money.
This isn’t a uniquely Indian problem, either. It hits every emerging market competing for the same pool of global capital, which is one reason several Asian markets fell alongside India through this period. (If you are not sure how the Sensex and Nifty 50 are even built, we have broken that down separately.)
Where does the money actually go?
This isn’t just theory — the money movement shows up in hard numbers. Foreign Portfolio Investors (FPIs), the big institutional money that flows in and out of Indian markets from abroad, pulled out roughly ₹20,974 crore from Indian equities in September 2026 alone, up to 18th September (also reported here), after two months of buying in July and August. That single month’s selling already added up to a large chunk of everything FPIs had bought back in through the year.
A meaningful part of why India feels this so directly: a large share of the foreign money invested in Indian equities originates from US-based funds. When US Treasuries suddenly look this attractive, that pool of money doesn’t need to go looking very far for a “safer” alternative — it’s sitting right at home.
There’s a second, related effect. As foreign investors sell Indian shares and convert their rupees back to dollars to chase US yields, it adds pressure on the rupee, which was trading close to the 96-per-dollar mark — a multi-year low — around this period, making imported goods, including oil, costlier still. (We have also looked at how NRIs and the rupee connect through FCNR deposits, if you want to go deeper on that side of things.)
Why are US bond yields so high right now, anyway?
Worth a quick word on this, since it’s not really about India at all. A few things have pushed US yields up through 2026: oil prices spiking on the West Asia conflict and stoking inflation worries; a US economy that has stayed surprisingly strong; and, underlying it all, growing unease among bond investors about the sheer size of US government debt, which crossed $40 trillion for the first time in August 2026, while Washington keeps spending well more than it collects in taxes each year. When investors worry a borrower is taking on too much debt, they demand a higher interest rate to keep lending — the same logic that applies to a bank charging a stretched borrower more.
None of this is a verdict on India’s economy or on any Indian company’s fundamentals. It’s a global capital-flows story that happens to have a very local effect on the price you see on your trading app.
What should this mean for you as an investor?
This kind of fall is about where global money is choosing to sit, not necessarily about anything having gone wrong with the businesses you own shares in. Selling in a panic on a day like this, driven by a story about American bonds, is rarely the right response for a long-term investor.
It’s also worth remembering this didn’t happen in one day. Indian markets had already been correcting for several weeks before this news cycle — the 28th September fall added to that, rather than starting it from scratch.
Finally, this is a good reminder of something easy to forget: your Indian mutual fund or stock portfolio doesn’t exist in a bubble. It competes, every single day, with every other place in the world large investors could park their money — including, apparently, a US government bond.
This article is for general information and educational purposes only, and should not be taken as investment advice. Market figures, yields and index levels move quickly and may have changed by the time you read this. Every effort has been made to check the facts and figures here against reliable sources, but any errors in summarizing them are the author’s own.
Key takeaways
- The link: A US bond yield is the interest rate the US government pays to borrow. With the 10-year yield at around 5.1% to 5.2% in late September 2026, its highest level in nearly two decades, a virtually risk-free return raises the bar that Indian stocks must clear to attract global money.
- The money flows: Foreign Portfolio Investors pulled out roughly ₹20,974 crore from Indian equities in September 2026, up to 18 September, after two months of buying. On 28 September 2026 the Sensex closed down 1,124 points (1.52%) at 72,771.72.
- What it is not: The article describes this as a global capital-flows story about where big money chooses to sit, not a verdict on India’s economy or on any Indian company’s fundamentals.
Frequently asked questions
When the US government needs to borrow money, it sells bonds, which is a loan from the buyer to the government. The yield is the interest rate on that loan, expressed as a percentage per year. The most quoted one is the 10-year US Treasury yield, which was around 5.1% to 5.2% in late September 2026.
Nobody seriously expects the US government to fail to repay this kind of debt, so a yield above 5% is considered virtually risk-free. That raises the bar that Indian stocks, and every other risky investment, must clear to attract the same global money. It affects every emerging market competing for the same pool of capital.
Foreign Portfolio Investors pulled out roughly ₹20,974 crore from Indian equities in September 2026, up to 18 September. When foreign investors sell Indian shares and convert rupees back to dollars, it adds pressure on the rupee, which was trading close to 96 per dollar, a multi-year low, around this period. A weaker rupee makes imports such as oil costlier.
The article points to three things: oil prices spiking on the West Asia conflict and stoking inflation worries, a US economy that has stayed surprisingly strong, and growing unease about the size of US government debt, which crossed $40 trillion for the first time in August 2026.
Sources
Main sources
Business Standard – Stock Market Live Updates, 28 September 2026 — closing Sensex/Nifty figures and reasons cited for the fall
Business Standard – Rising US bond yields weigh on Indian stocks — US 10-year yield level and the risk-free vs. risk-asset mechanism
Business Standard – FPIs withdraw ₹20,974 crore from equities in September — FPI outflow figure for September 2026
Al Jazeera – US debt hits $40 trillion — US government debt figure, citing US Treasury data
Other sources
Stockpil – India Markets Today, 28 September 2026 — cross-check on Sensex/Nifty close
CNN Business – 10-year Treasury yield hits 5.1% for first time in 19 years — confirms the 19-year-high yield level
Business Standard – G-Sec yields surge; rupee nears 96/$ and HDFC Sky – Rupee quote, 28 September 2026 — rupee levels around 28 September 2026
The Federal – FPIs withdraw ₹20,974 crore from equities — cross-check on September FPI outflow figure
Forbes India – Why Rising Global Bond Yields Matter More Than Ever for India — background on how much of India’s FPI money originates from the US
YouTube references: video 1 (Firstpost), video 2 (News9)
I used Claude, an AI assistant, to rephrase my notes to make it reader friendly.